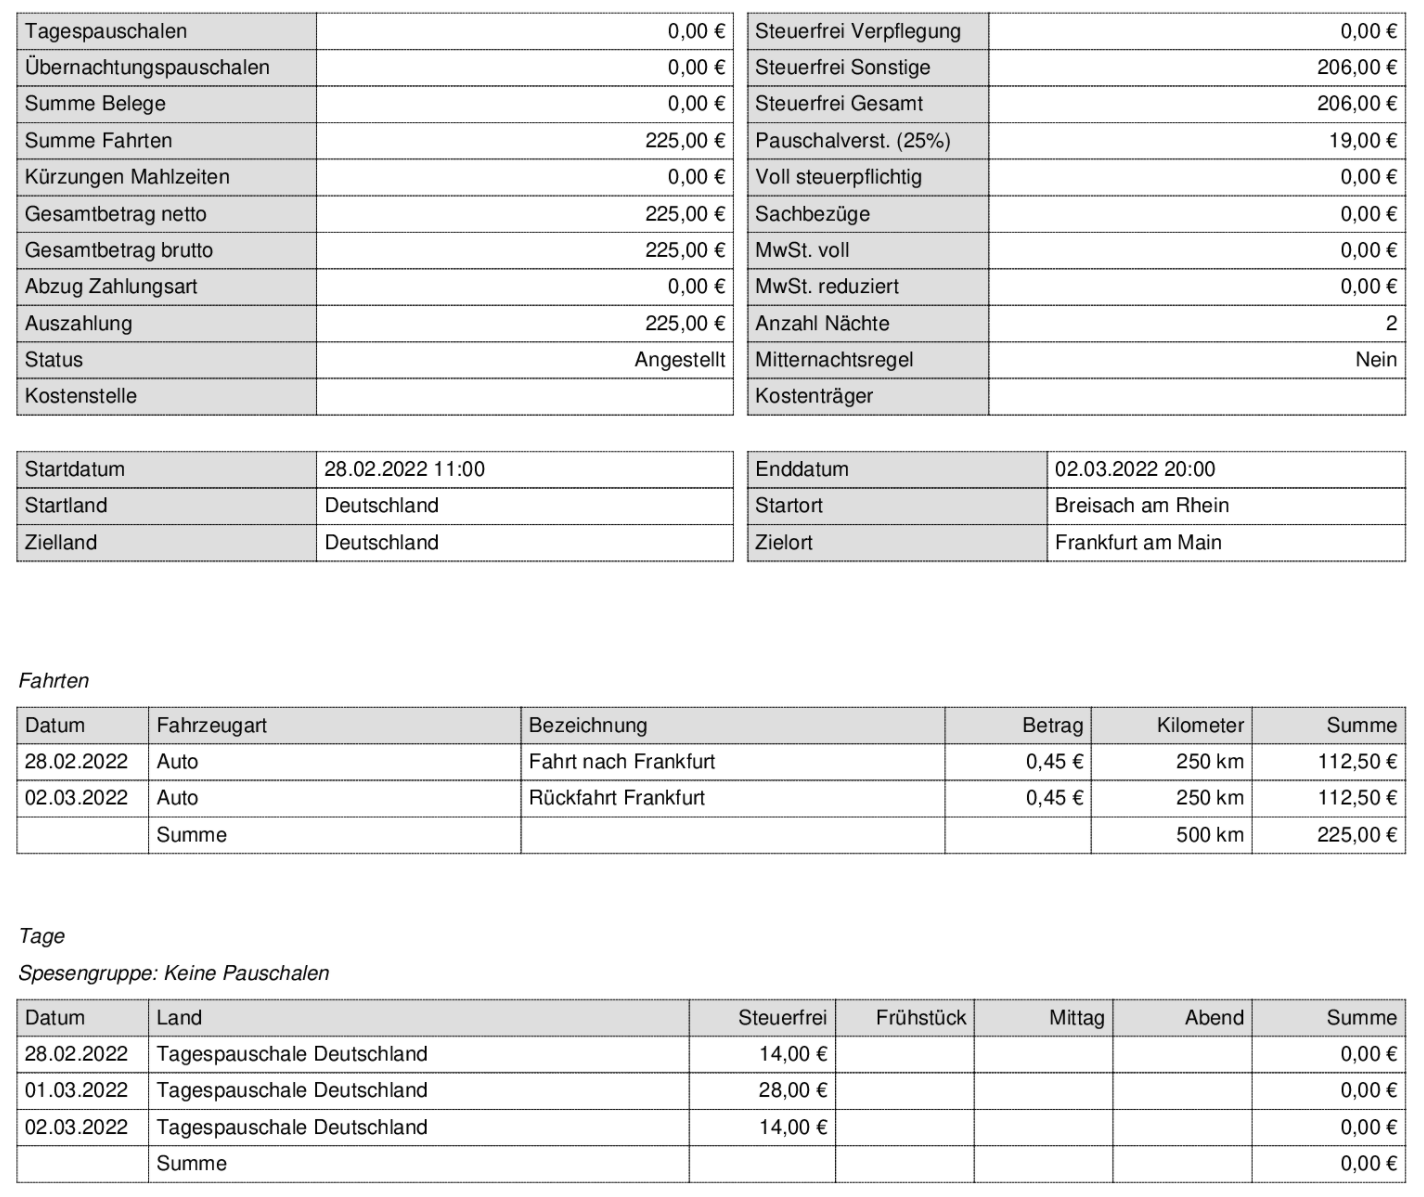
From a legal point of view, the individual types of expenses may be combined to determine the tax-free reimbursement amount (known as the total calculation, German: Gesamtrechnung). For the sake of simplicity, there are also no objections to treating the amount that exceeds the tax-free reimbursement amount uniformly as reimbursement for additional meal expenses, which can be taxed at a flat rate of 25%, provided that the 100% limit is not exceeded (R 40.2 (4) sentence 4 LStR, German Wage Tax Guidelines).
The Wage Tax Guidelines state the following:
"For the sake of simplicity, there are also no objections to treating the amount that exceeds the tax-free reimbursement amount uniformly as reimbursement for additional meal expenses, which can be taxed at a flat rate of 25% within the limits of Section 40 (2) sentence 1 no. 4 EStG." (translated)
A mileage rate for travel cost reimbursement that exceeds the statutory allowances can be taxed at a flat rate to the extent that, in an total calculation with the meal allowances of the corresponding business trip, the amount of the meal allowances is not exceeded by more than 100%.
Setting in Spesenfuchs
Whether Spesenfuchs uses the total calculation is set under Settings → Accounting → Calculation with the option 25% flat rate balance:
- Option enabled: Spesenfuchs adds together the meal allowance, the travel allowance and the accommodation allowance of a trip. The amount that exceeds the sum of the tax-free allowances is taxed uniformly at a flat rate of 25%, provided that the 100% limit is not exceeded.
- Option disabled: Only the meal allowances are used as the basis for the 25% flat-rate tax.
You can find more information about this and other settings under Calculation basis.
Example
The example uses the meal allowances currently applicable to trips within Germany. You can find the current amounts under Meal allowances.
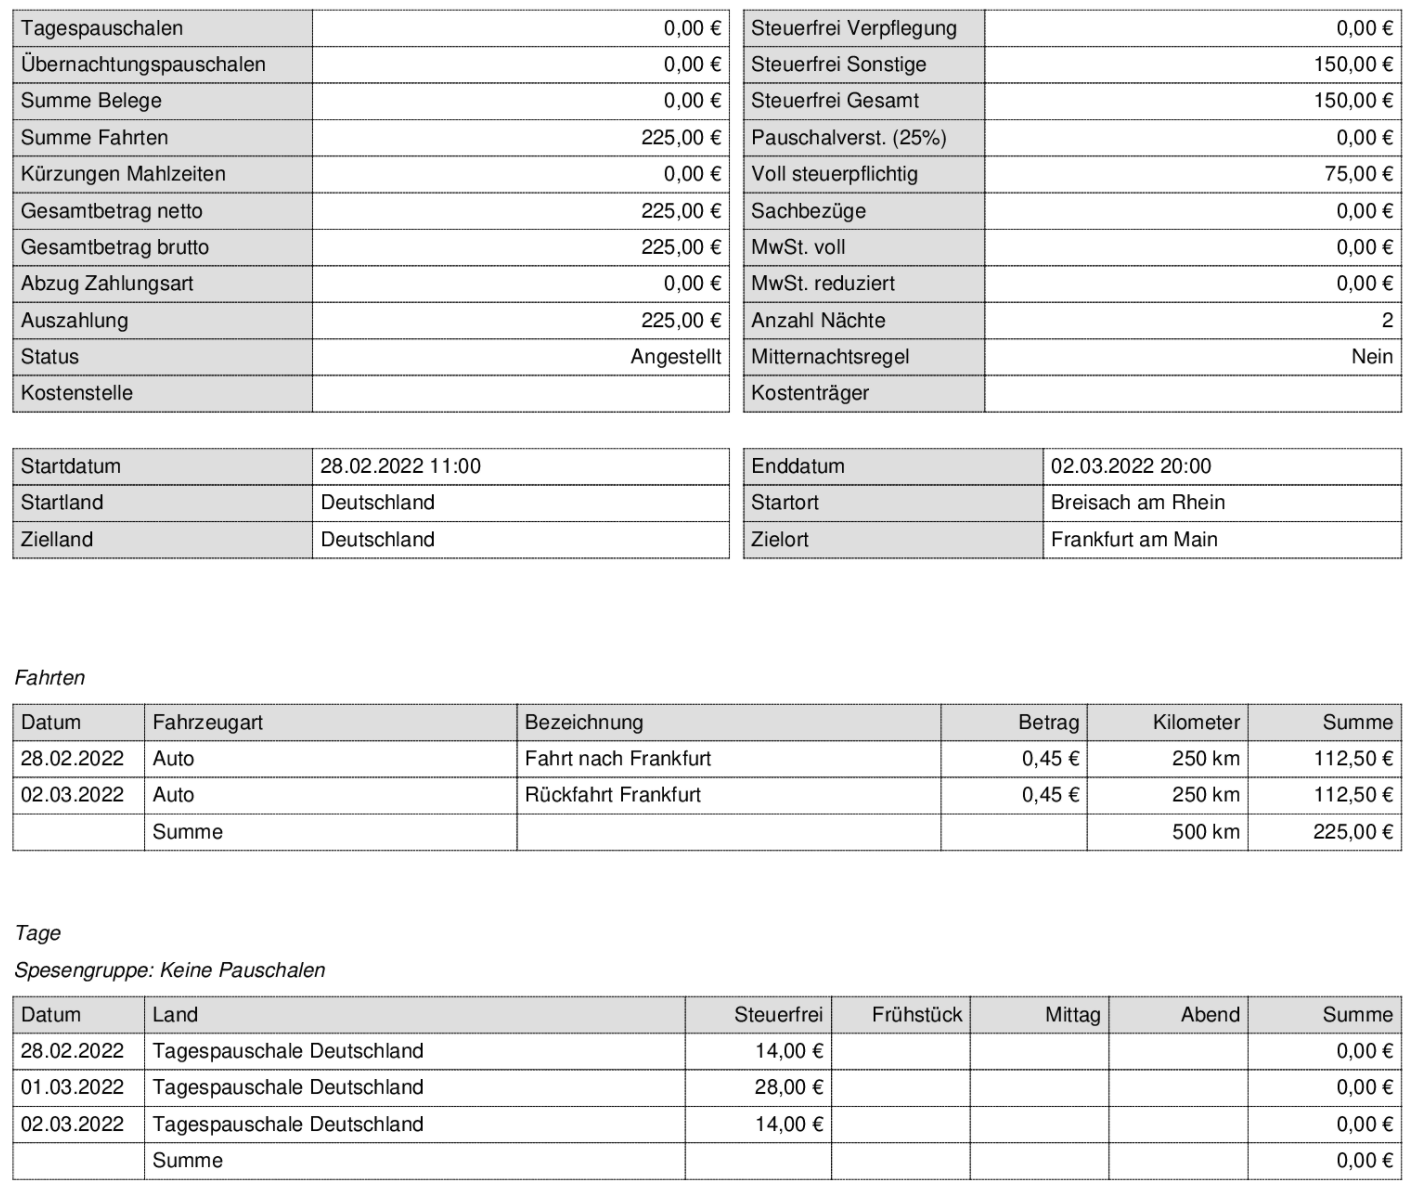
Due to a business trip from Monday 10 a.m. to Wednesday 7 p.m. with free accommodation and meals at a business partner's guest house, an employee only receives a flat-rate travel cost reimbursement of €225, based on a total distance of 500 km with a private car.
Total calculation not used – 25% flat-rate taxation disabled
Result: The following are tax-free:
| Travel cost reimbursement (500 km × €0.30) | €150.00 |
| Meal allowances | €0.00 |
| Total | €150.00 |
The excess amount of €75.00 (€225.00 − €150.00) must be taxed in full at the employee's individual tax rate.
Total calculation used – 25% flat-rate taxation enabled
Result: The following are tax-free:
| Travel cost reimbursement (500 km × €0.30) | €150.00 |
| Meal allowances (€14 + €28 + €14) | €56.00 |
| Total | €206.00 |
The excess amount of €19.00 (€225.00 − €206.00) can be taxed in full at a flat rate of 25% (maximum €56.00).